5 min read
An HVAC or plumbing company can stay busy while its employees misunderstand how the business makes money. A large service invoice does not reveal the costs behind it, and a full schedule does not explain what remains as profit.
Without financial context, employees fill the gaps themselves. Owners may see necessary operating reserves while technicians see money that should fund raises, creating tension around compensation, pricing, and expectations.
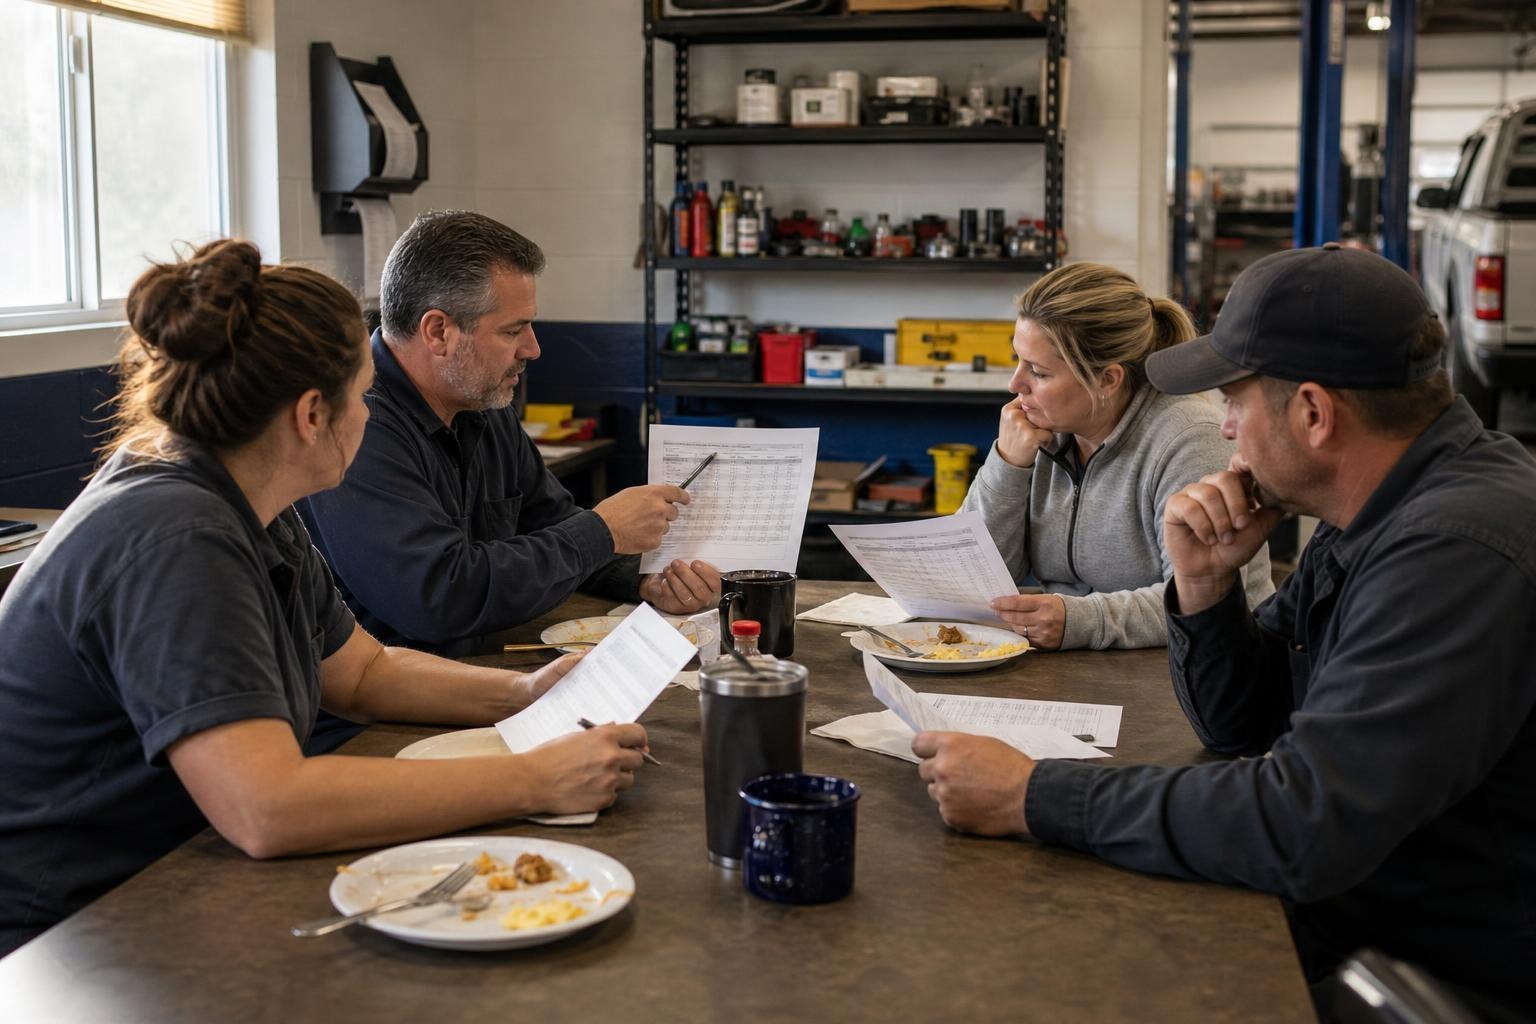
Tucker Yarbrough, CFO and co-owner of Yarbrough & Sons Heating, Cooling & Plumbing, brings experience running a service truck. His company practices financial transparency by reviewing its results with employees at a monthly breakfast.
The sections below break down how to share useful financial information, connect compensation to clear measures, preserve customer choice, and protect departmental profitability. The goal is to make the numbers understandable enough to guide everyday decisions.
Make financial transparency useful to HVAC employees
For an owner facing questions about prices or raises, sharing a financial statement is only a starting point. Employees also need an explanation of what the figures mean and which decisions affect them.
Separate revenue from money available to spend
A service ticket is revenue, not a measure of what the owner takes home. Materials, labor, and overhead all stand between the invoice and net profit.
Profit also has a job after the books close. Money retained in the business supports payroll, operating needs, and future growth rather than automatically becoming an owner's personal income.
Share a consistent financial picture
Yarbrough and Sons shares line items above gross margin, explains overhead, and walks through net profit. It does not disclose every granular personnel detail.
- Review revenue and direct costs.
- Explain the gross margin result.
- Describe the costs included in overhead.
- Show the resulting net profit or loss.
That sequence gives employees a repeatable way to understand performance. Clear disclosure boundaries keep the discussion focused without requiring every personnel expense to become public.
Explain difficult months instead of avoiding them
The company's first four monthly disclosures showed losses, beginning in October and continuing through January. Leadership explained the seasonal context, and nobody quit during that initial stretch.
The lesson is not that employees will welcome every result. It is that unfavorable numbers need context, including why stronger months matter and how the company plans around weaker periods.
A useful financial review answers questions that employees already have. It replaces an unexplained total with a clearer picture of how the business operates.
Give technicians a measurable path to higher pay
Compensation discussions become more concrete when employees know the calculation before asking for a raise. The underlying measure must be clear enough for both the technician and manager to follow.
Define the labor percentage precisely
At Yarbrough and Sons, service technicians and plumbers remain hourly employees. The company compares gross monthly pay with eligible revenue produced from each technician's truck.
- Use gross pay for the month.
- Compare it with that month's truck revenue.
- Exclude system flips and large plumbing sales.
The company's target is a labor percentage at or below 25%. A result above that threshold prompts a discussion, rather than leaving the employee to guess what needs attention.
Explain how performance changes compensation
Under this model, quarterly performance below 25% leads to a raise. An employee finishing the year below the threshold can receive a makeup check bringing pay up to that share of eligible revenue.
These are company-specific rules, not universal pay benchmarks. Their practical value is the visible connection between the calculation, the review schedule, and the compensation decision.
Make the promise verifiable
New hires are encouraged to ask coworkers whether they have received makeup checks. Existing employees can confirm that the compensation arrangement has produced actual payments.
That turns a recruiting promise into something applicants can investigate. It also gives managers a more concrete basis for pay discussions than tenure or an undefined feeling about performance.
The percentage alone is not the compensation system. Employees also need its exclusions, review periods, and payment rules explained consistently.
Connect profitable service with informed customer choice
A financial target should not become pressure to sell an unnecessary replacement. The stronger connection is between thorough service, clear explanations, and a homeowner's ability to choose the next step.
Distinguish restoring operation from explaining condition
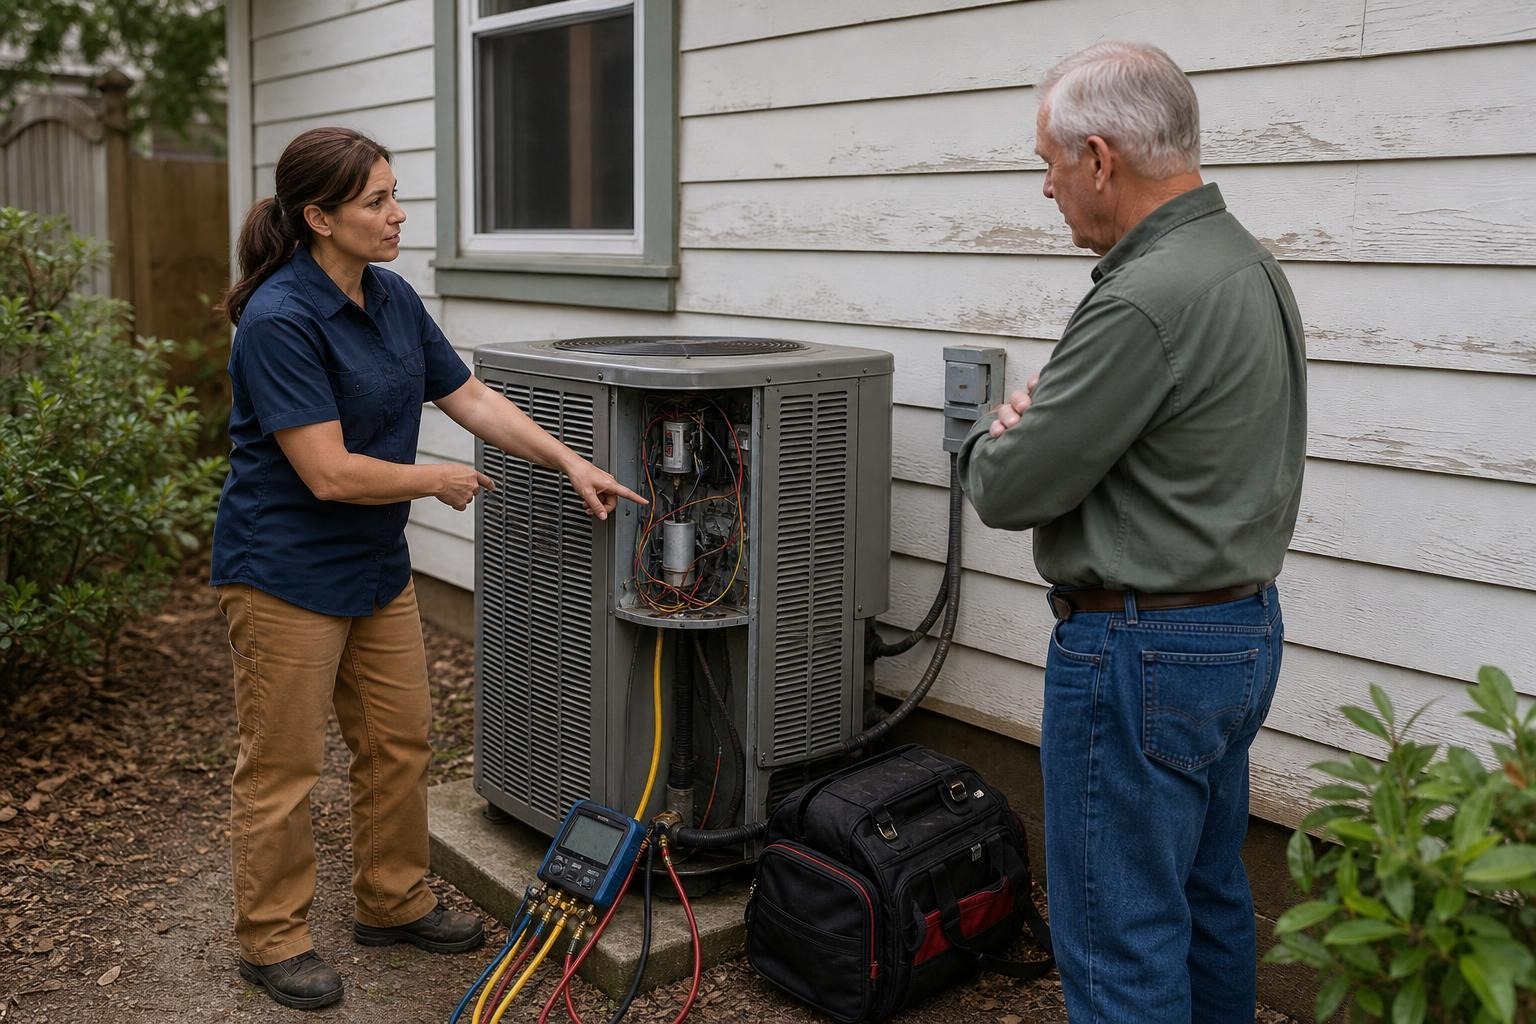
Replacing a failed capacitor may restore operation without resolving every concern found during the visit. If a technician notices additional warning signs, documenting them internally is not the same as explaining them to the homeowner.
In one company example, a technician noted a compressor concern after replacing a capacitor. The compressor later failed, requiring another visit and leaving a different technician to handle the replacement.
Use a trigger to start a discussion
The company's 12 or 12 rule starts a replacement discussion when equipment reaches 12 years old or a repair reaches $1,200. It does not require the customer to replace the system.
Those thresholds are a company practice, not a universal equipment-life standard. Their purpose is to make the discussion easier to initiate while leaving the purchasing decision with the homeowner.
Keep repair available as a legitimate choice
An in-house residential project manager supports technicians with both replacement and repair discussions. A homeowner who declines replacement can still consider appropriate repair work.
- Explain the condition found.
- Discuss relevant repair and replacement options.
- Ask which next step the homeowner prefers.
Leaving an estimate is not the same as discussing what happens next. A clear explanation gives the customer a decision to make rather than paperwork to interpret alone.
Profitable service and customer choice need not compete. The practical standard is complete communication, not replacement at any cost.
Protect department margins and collect the cash
Company-wide results can obscure a department that depends on another department's profits. Financial accountability becomes more useful when managers can see their own costs, overhead burden, and collection needs.
Set material targets by department
Yarbrough and Sons reviews materials against each department's revenue during its monthly breakfast. Its targets differ because service, plumbing, and replacement work have different material requirements.
- HVAC service and maintenance: below 20%.
- Plumbing: approximately 15%.
- Residential HVAC replacement: approximately 25% to 30%.
These figures describe that company's operating targets, not guaranteed industry benchmarks. Managers use departures from the targets to investigate costs rather than treating revenue growth alone as success.
Recognize where overhead originates
Service requires dispatchers, customer service support, management, and field coordination. The company targets roughly 60% service gross margin because that department carries a substantial overhead burden.
Its operating principle is that each department should be profitable on its own. Depending on installation revenue to cover service losses makes the business more exposed when replacement work slows.
Close the gap between earnings and available cash
Knowing margins does not replace collecting payment. Accounts receivable must turn into cash, and reserves give the company room to make operating decisions during leaner periods.
That distinction also belongs in employee financial education. A profitable statement and cash available for payroll answer different questions, so the monthly discussion should not stop at net income.
Department-level accountability makes performance easier to locate. Collections and reserves determine how much flexibility those results actually provide.
Conclusion
Financial transparency works best as an operating practice, not an occasional disclosure. Its value comes from connecting the company's results with decisions employees can understand and influence.
First, establish a consistent financial picture with clear disclosure boundaries. Explain revenue, costs, overhead, and retained profit so employees do not have to invent their own account of the business.
Second, make performance expectations specific enough to guide compensation and service discussions. Clear rules should support accountable work while preserving the customer's right to choose.
Third, examine profitability within departments and follow earnings through to collection. A strong company-wide total does not remove the need to understand cost allocation, receivables, and reserves.
A practical starting point is one monthly financial review with a defined agenda. Identify which numbers employees need, explain one decision those numbers affect, and return to the same measures the following month.
Frequently asked questions
What does financial transparency mean for an HVAC company?
It means sharing and explaining business results so employees understand revenue, costs, and profit. The model described here uses a monthly financial review.
Does sharing the books require disclosing every employee's pay?
Not in the approach described here. The company explains financial performance without opening every granular personnel expense to the team.
Is a 25% labor target a universal compensation rule?
No. It is this company's target, calculated using gross pay and defined eligible truck revenue, with specific exclusions and review rules.
Does a 12-year-old HVAC system have to be replaced?
No. The company's age threshold starts a discussion about options; it does not mandate replacement or remove the homeowner's choice.
Why does a profitable company still need cash reserves?
Reported earnings do not ensure that customer payments have been collected. Reserves support ongoing obligations and provide flexibility during leaner periods.